The Quiet Money in Britain’s White Lines
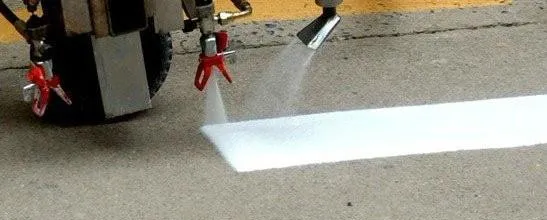
Photo: Summysung, CC BY-SA 4.0, via Wikimedia Commons
Road markings are the most ignored piece of infrastructure in Britain. You notice them when they are wrong: a faded give-way line, a motorway lane that seems to wander, a box junction that has become a suggestion. The rest of the time they disappear into the tarmac — which is exactly why the businesses behind them are worth a closer look.
At Akkail, we like a niche that looks dull from the outside and turns out to be structurally interesting. Road marking is that niche. It sits at the intersection of public procurement, safety regulation, specialist labour and a surprisingly concentrated supply chain. The product is cheap relative to the road. The consequences of getting it wrong are not.
A safety product dressed as paint
The first thing to understand is that the white line is not paint from a DIY shed. Most high-volume road markings use thermoplastic materials, applied hot, with reflective glass beads embedded in the surface so headlights bounce back at night. Cold plastics, epoxies and preformed tapes all have their place. Each has different durability, cost and weather requirements. Each needs crews who know what they are doing.
That matters because road marking is a safety product. A line that is in the wrong place, too faint or poorly reflective is not a cosmetic flaw. It is a risk. Highways authorities and their contractors therefore buy against specifications, not vibes. They want certified materials, tested retroreflectivity, documented method statements, traffic management plans and insurance. They want crews who can work at night, in closures, without creating a second safety incident.
Those requirements create a moat. Anyone can buy a marking machine. Not everyone can get on a council framework, keep a fleet compliant, manage a night-time workforce and carry the liability. The barriers are not glamorous, but they are real.
The £1bn question
How big is the UK road marking market? It depends where you draw the boundary. Narrowly, you might count thermoplastic supply and application on local roads, motorways and major schemes. More broadly, you include road studs, anti-skid surfacing, temporary markings, line removal and the associated traffic management. Estimates vary, but the sector is often discussed as something in the region of £1bn a year once maintenance, major projects and the surrounding supply chain are rolled in.
The exact number matters less than the structure. This is not one market. It is a patchwork of contracts: local highway authority term maintenance, National Highways supply chain work, utility reinstatements, new housing estates, retail parks, airports, ports and private estates. Some work is procured through big frameworks. Some is subcontracted down the chain. Some is still won by regional firms with deep local knowledge and a yard full of equipment.
That patchwork is why pricing power is uneven. On a large framework, the client holds the cards. On a remote rural road with a tight weather window and a contractor already mobilised nearby, the contractor has more leverage. Road marking is not a licence to print money. But nor is it a commodity free-for-all.
Why councils and contractors do not simply buy the cheapest line
Public procurement is often caricatured as a race to the bottom. In road marking, it is more complicated. Councils and contractors are buying assurance as much as they are buying material. A failed marking job can mean rework, complaints, insurance claims and reputational damage. Switching suppliers to save a few percentage points is rarely worth the operational risk.
That gives incumbents an advantage — but not immunity. Public budgets are tight, and highway maintenance is always competing with social care, waste collection and everything else a council has to fund. Contractors face rising costs for resin, glass beads, fuel, vehicles and labour. They also carry the working capital burden of public sector payment terms, which can be long even when they are improving.
So the financial picture is more nuanced than ‘high margins’. Gross margins on specialist application can look healthy. Net margins depend on fleet utilisation, winter weather, mobilisation costs, contract indexation and how well the firm manages a workforce that often works unsocial hours. The best operators are not just good at painting lines. They are good at scheduling, logistics and risk.
The consolidation trade
The sector has been quietly consolidating for years. Larger groups have bought regional operators to add crews, depots and framework positions. Private equity has circled, attracted by the classic ‘boring industry’ pitch: recurring maintenance, regulation, safety-critical demand and a fragmented base of family firms with succession questions.
Consolidation can make sense. A bigger group can spread fleet costs, invest in training, bid for larger contracts and negotiate better material prices. It can also reduce local competition. When a handful of players control key depots and framework slots, councils have fewer credible alternatives. That is not automatically bad — scale can improve reliability — but it is worth watching. ‘Boring’ does not mean ‘uncompetitive’.
The supply chain adds another layer. Thermoplastic materials, glass beads and resins come from a relatively small number of suppliers. Energy costs matter. So does haulage. A road marking firm is therefore exposed to industrial input prices as well as public spending cycles. The smart ones build indexation into contracts and keep a close eye on stock. The less smart ones discover that a fixed-price contract and a cold snap do not mix.
What boring Britain teaches us
Road marking is a useful antidote to the idea that interesting businesses must be tech businesses. It is a sector built on recurring need, technical specification and operational discipline. It rewards firms that invest in training, equipment and relationships. It punishes firms that treat safety as paperwork.
It also shows why ‘overlooked’ does not mean ‘easy’. The barriers to entry are high, the clients are demanding and the margins are exposed to forces outside the boardroom. For investors, it is a reminder that consolidation stories in unglamorous sectors can be compelling — and that public sector concentration is a risk as well as a moat.
For the rest of us, the white line is a small lesson in how British industry actually works. The loudest sectors get the headlines. The quiet ones keep the roads safe, the contracts moving and the money turning. You just have to look down.